


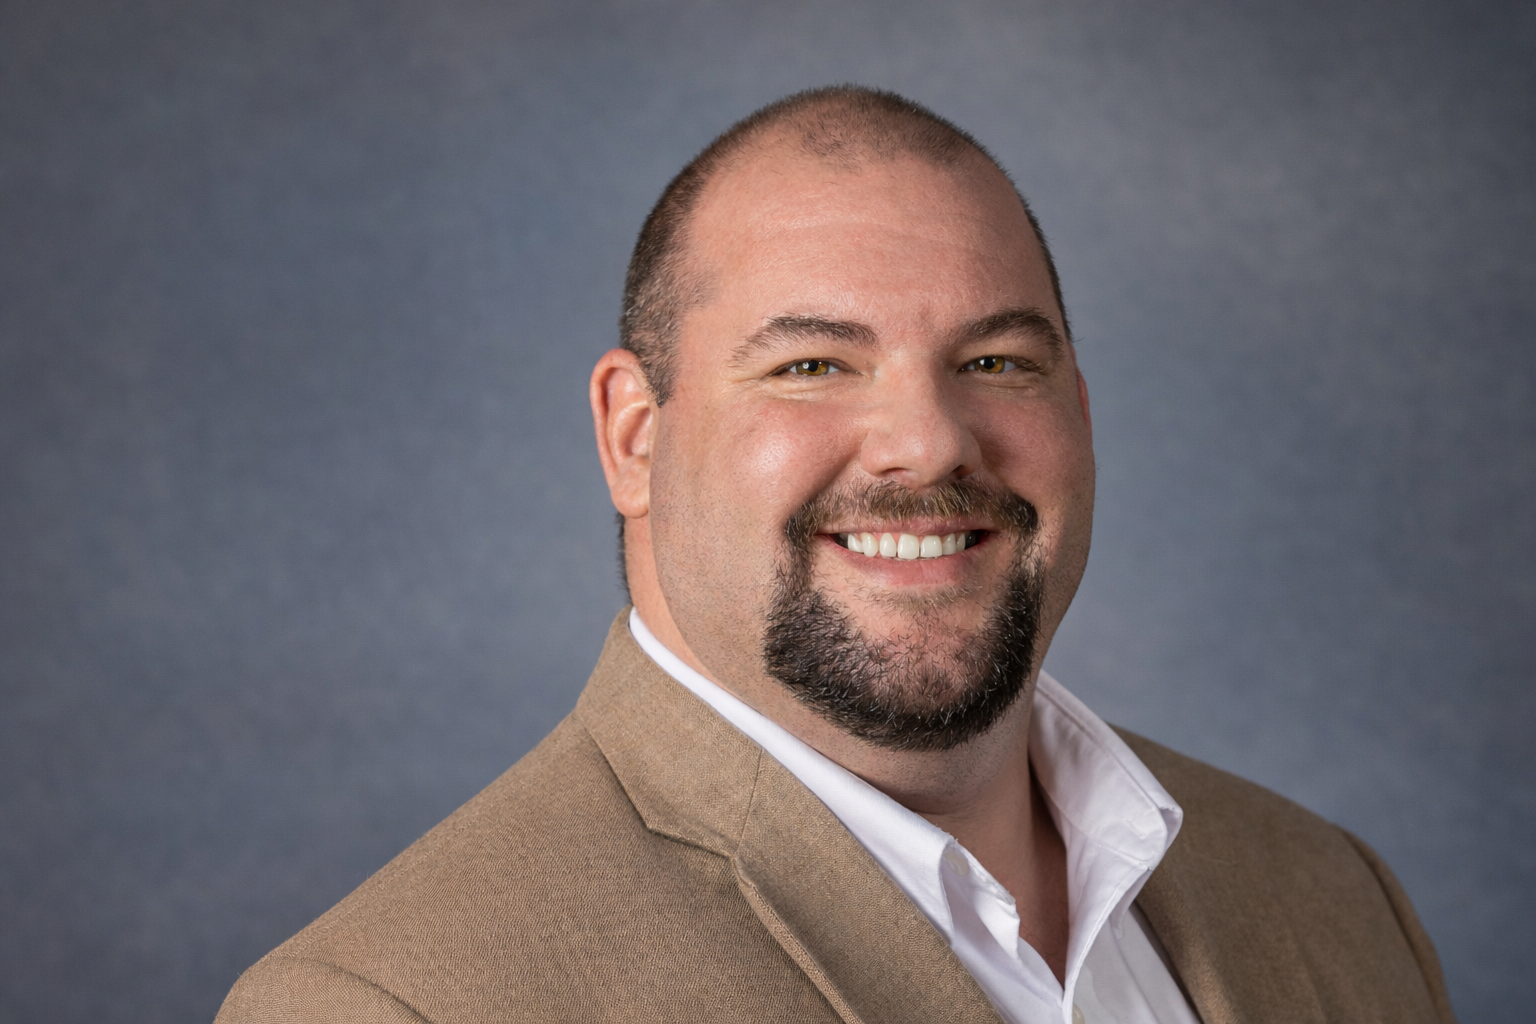
The Grants Pass Tribune sits down with Dustin Calvo, Josephine County’s appointed treasurer and a candidate seeking election to continue in the office, to examine how he would protect taxpayer money, administer property tax collections and prepare the treasury for financial risks.
Calvo served as chief deputy treasurer before his appointment and now carries out both treasury and tax collection responsibilities. The Tribune requested the same questions from Calvo and his opponent, Simon Hare, with an October 9 deadline. Calvo’s responses address his qualifications, governmental accounting, investment decisions, property taxes, economic conditions and safeguards against fraud. His answers appear below in full, with corrections limited to grammar, spelling and punctuation.
Oliver: What specific education, professional experience and demonstrated financial responsibilities qualify you to serve as Josephine County Treasurer? Explain your understanding of governmental fund accounting, including the differences among cash balances, budget authority and money legally available for expenditure. How would you verify that restricted funds and money held for other taxing districts remain properly accounted for, and what experience prepares you to identify and resolve a discrepancy among bank statements, investment records and the county’s general ledger?
Dustin Calvo:
“My strongest qualification is that I am doing this work now. I served as Josephine County’s chief deputy treasurer before being appointed treasurer, and I currently carry out both the treasury and tax collection functions. My responsibilities include safeguarding county and taxing district money, managing cash and investments, accounting for receipts, and ensuring property tax collections are distributed accurately. My relevant education and training include an undergraduate certificate in accounting, seven years in private-sector accounting, and multiple training sessions through state associations.
Governmental accounting requires more than checking whether there is money in the bank. A cash balance shows what has been received and remains on hand. Budget authority is the legal permission to spend up to an adopted amount for an approved purpose. Money legally available for a particular expenditure must satisfy both tests and any additional restrictions on its use. Cash held for a school district, city, or other taxing district is not available for the county to spend. Neither is a restricted grant balance available for an unrelated county expense.
I would verify those distinctions through fund-level records, documented restrictions, the tax collector’s distribution schedules, and regular reconciliations. Bank balances, investment and custodial statements, the county’s general ledger, and amounts owed to other districts must agree or have a documented timing difference. If they do not, I would trace the transactions to their source, identify whether the issue is a bank item, posting error, valuation difference, or misallocation, and work with Finance and the affected district to correct it. The person reviewing the reconciliation should be independent of the person who initiated the transaction. During the past year, I have located and corrected several errors that were caused by my predecessor during his short tenure.
That is how I approach this office: account for whose money it is, document where it went, and resolve differences rather than carrying them forward.”
Oliver: If elected, how would you manage Josephine County’s investment portfolio to protect principal, maintain sufficient liquidity and earn an appropriate return within Oregon law and county policy? Explain how you would evaluate credit quality, investment duration, maturity schedules, issuer concentration and custodial safeguards before approving an investment. How would you respond to rising interest rates or an unexpected need for cash that could require selling a security at a loss, and what information would you report publicly so voters could evaluate your investment decisions?
Dustin Calvo:
“My investment priorities are protection of principal, enough liquidity to pay obligations when due, and then an appropriate return. I already use a maturity ladder so investments come due at different times instead of tying up the county’s cash on one date. I compare available opportunities, including the Oregon Local Government Investment Pool, within state law and the county’s adopted investment policy. The Board has a role in adopting policy; my job is to carry it out and make prudent individual decisions within it.
Before approving an investment, I would verify that the instrument and its maturity are permitted, assess the issuer’s credit quality, and compare its yield with alternatives of similar risk and duration. I would check the total exposure to that issuer and institution, the maturity schedule against projected cash needs, and the arrangements for holding the security. For bank deposits, I would verify applicable insurance and Oregon public funds collateralization requirements. I would retain the quotes, analysis, approval, and transaction record so the decision can be reviewed later.
Rising rates can reduce the market value of an existing fixed-rate security even when it is expected to repay at maturity. I would not chase a higher quoted yield by locking up money needed for operations. A ladder and readily available cash reduce the chance that the county must sell at a loss. If an unexpected need arose, I would first confirm whose funds may legally be used, update the cash forecast, and compare lawful sources of liquidity before recommending a sale. Any realized loss would be documented and reported, not hidden behind a discussion of overall yield.
Voters should be able to see the portfolio’s balances, holdings by type, maturities, earnings, and compliance with policy, along with an explanation of material changes or losses. The county already posts quarterly treasurer reports. I want those reports to help residents understand the decisions as well as see the numbers.”
Oliver: What is your understanding of how Oregon’s Measures 5 and 50 affect assessed property values, tax compression and the revenue available to Josephine County and other taxing districts? Explain how you would account for payment discounts, installment payments, delinquencies, appeals and refunds when forecasting collections and administering distributions. If elected, what would you do to improve the accuracy, timeliness and transparency of this work, and how would you distinguish your authority as treasurer from the responsibilities of the assessor and Board of Commissioners?
Dustin Calvo:
“Measure 50 generally limits annual growth in a property’s maximum assessed value to 3 percent, with exceptions such as new construction. The taxable assessed value is generally the lower of that maximum and the property’s real market value. Measure 5 then limits certain education and general government taxes based on real market value. When taxes exceed those limits, compression reduces the amount billed. That means neither an increase in market value nor a district’s requested levy automatically produces the same increase in collections.
A useful revenue forecast begins with the certified tax roll after applicable limits and compression, then accounts for how and when taxpayers actually pay. Full payment by the November deadline generally qualifies for a 3 percent discount; taxpayers may also pay in installments. I would use prior collection patterns to estimate the November, February, and May receipts, then separately track delinquencies, later collections, interest, corrections, appeals, and refunds. An amount billed is not the same as cash received, and a pending appeal can change the final amount.
As treasurer and tax collector, I would continue reconciling receipts to the tax records and bank deposits, checking the statutory allocation schedule, and distributing collections to the proper districts on time. I would track exceptions and corrections so districts can understand changes in their payments. I would also make reporting clearer about taxes imposed, cash collected, discounts, outstanding amounts, and distributions.
The assessor determines values and prepares the assessment and tax roll. The Board adopts the county budget and makes policy and spending decisions within its authority. The treasurer safeguards, accounts for, invests, and distributes money; as the county’s designated tax collector, I also administer collections. I would work closely with the assessor and Board while keeping those responsibilities clear.”
Oliver: How would you prepare Josephine County’s treasury for delayed tax collections, declining investment income or other economic conditions that reduce available cash? Describe the forecasting methods, liquidity reserves and stress tests you would use to determine whether the county could meet its obligations when due. How would you distinguish a temporary cash shortage from a continuing imbalance between revenue and expenditures, what legal limitations would govern any proposed borrowing between funds, and when would you notify county officials and the public of a developing financial problem?
Dustin Calvo:
“I would maintain a rolling cash forecast by fund, updated with actual receipts and payments. It should show payroll, debt payments, distributions owed to taxing districts, grant reimbursements, investment maturities, and the seasonal pattern of property tax collections. A countywide cash total alone can be misleading because money belonging to another district or restricted to a particular use cannot simply cover the county’s bills.
I would test that forecast against delayed property tax receipts, slower grant reimbursements, lower investment income, and unexpectedly high expenses. The result should tell us how much immediately available cash each fund needs and when an investment must mature. I would review those assumptions with Finance and adjust the investment ladder before a shortage forces a rushed decision.
A temporary cash shortage has an identifiable timing cause and a credible source and date for repayment. A continuing imbalance means recurring expenditures exceed recurring revenue; moving cash between funds will not solve it. If an interfund loan were proposed, I would require review of the source fund’s restrictions, a governing body resolution, a lawful purpose, a repayment plan, and confirmation that the loan will not impair the source fund’s obligations. I would not treat money held for other taxing districts as a reserve for county operations.
I would notify Finance and the Board promptly when a forecast shows a material problem, while there is still time to respond. I would explain the issue publicly once the facts and appropriate response are established, including its size, timing, affected funds, and whether it is a timing gap or a structural budget problem. The public should hear about a developing risk before it becomes a missed payment.”
Oliver: If elected, what specific controls would you require to protect county money against fraudulent payments, unauthorized account changes, internal misuse and cyberattacks? Explain how you would apply segregation of duties, independent verification of banking changes, dual payment authorization, multifactor authentication and auditable transaction records. How would you maintain essential treasury operations if financial systems became unavailable, verify the accuracy of restored records and demonstrate that your safeguards work? Identify the measurable improvements you would seek during your first year and how voters could evaluate your progress.
Dustin Calvo:
“Protecting public money requires controls that operate on ordinary transactions, not just a policy binder. I would maintain separation between the people who set up a vendor or bank account, approve a payment, release it, and reconcile it. Changes to payment instructions should be verified through a trusted phone number or other independently established contact, never solely through the email requesting the change. Sensitive payments should require two authorized approvals, and access to banking and financial systems should use multifactor authentication, individual accounts, limited permissions, and prompt removal when a person changes roles.
I would require transaction logs that show who requested, changed, approved, and released a payment. Reconciliations should be completed and reviewed on a defined schedule, with unresolved items assigned and followed to closure. Banking alerts and payment controls should help detect unusual activity quickly. I would coordinate these measures with Finance, IT, the banks, and the county’s auditors because the treasurer cannot secure a connected financial system alone.
If the systems went down, the office would need current contact lists, secure copies of essential records, documented approval procedures for critical payments, and a tested way to communicate with the bank. When service returned, we would compare bank confirmations and transaction records with restored system data, account for every payment made during the outage, and independently review exceptions before treating the records as complete.
In my first year of a new term, I would document the current controls and establish measurable targets: reconciliations completed and reviewed on time, payment and account changes independently verified, access rights reviewed regularly, exceptions resolved within defined periods, and at least one tested recovery exercise. I would report progress and material findings in a way the public can evaluate without publishing details that would help someone defeat the safeguards.”
Oliver, Bonus Question 8: If you received $25,000 from Josephine County under a contract, failed to fulfill your contractual obligations and knew that you were required to repay the money, how would you justify refusing to do so while asking voters to entrust you with the county treasury? What steps would you take to resolve the debt, and what standard of financial accountability should voters expect from you when your personal interests conflict with your obligations to taxpayers?
Dustin Calvo:
“I respectfully decline to answer Bonus Question 8 because it directly concerns my opponent and is not pertinent to my campaign. I am committed to running a campaign that highlights my merits and character and not any real or perceived deficits of my opponent. I appreciate the opportunity to answer questions about my qualifications, how I would manage the county treasury, and the standards of accountability I would bring to the office.”
Calvo’s opponent, Simon Hare, did not respond to the October 9 deadline. His nonresponse leaves readers without his answers about the accounting practices, investment decisions, tax administration and financial safeguards he would bring to the office.
Hare’s unanswered response also leaves Tribune’s questions about his unresolved $25,000 budget officer contract payment unaddressed. The newspaper has previously reported that Hare received the payment for a 2025 budget assignment he left before completing. The bonus question gave both candidates an opportunity to address personal financial accountability involving county money; Calvo declined to discuss his opponent, while Hare submitted no response.